

Authored by

The operational reality behind one of retail alternatives' fastest-growing incentives.
Bonus shares—are they really a bonus? Operationally, no. When a firm considers bonus shares as a distribution tool, the approach should be cautious, well thought out, and partner driven. Bonus shares are not a shortcut to distribution. Used wisely during the private or seed phase, they are a strategic tool that can set up a product for future growth.
“Bonus shares are not a shortcut to distribution. They are a strategic tool, best deployed during a fund’s private or seed phase.” |
What is a bonus share?
In the world of retail alternative funds, bonus shares work as a strategic incentive rather than a simple corporate action. Unlike a traditional equity bonus issue that reaches every shareholder, bonus shares in retail alternatives are typically volume-based rewards for selling firms or large-scale investors who reach specific commitment milestones.
Sponsors who come from the private fund world will recognize the idea. Anchor and founder share classes reward early or catalyst investors for committing capital before a fund has proven itself. Bonus shares carry the same intent into interval and tender offer fund structures, though the registered wrapper adds layers of intermediary and reporting machinery that private funds never had to touch.
The milestones, triggers, and contractual language inside a bonus share agreement can create a complex and risky operating model with service partners when the design is wrong. A firm can build the best program in the world, but if no partner can adopt or administer the program across its full life, the program will not gain traction.
Part of the difficulty is structural. The registered fund ecosystem has no standardized transaction code that identifies a bonus share event or flags a bonus-eligible position. Allocation falls to the transfer agent as a largely manual exercise, and the manual effort ripples downstream to custodial platforms, wealth management systems, and performance reporting tools. Every party interprets the same event on its own, which is where inconsistency and operational risk take hold.
How does a sponsor design a bonus share program that avoids downstream failure? The answer starts with the product and distribution model.
Two paths: daily NAV/FundSERV vs. periodic NAV/AIP
There is no one-size-fits-all program. There are, though, guiding parameters every sponsor should know, and the first decision is the product and distribution model.
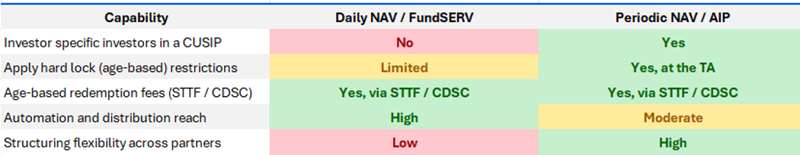
If you run a daily NAV product with FundSERV distribution intentions, your bonus share options and restrictions are extremely limited. FundSERV is a powerful utility for automation, expanded distribution, and paperless trading. FundSERV is also rigid and standardized by design. A sponsor has to build the program inside the framework of the utility, or major distribution partner access will not follow.
Daily NAV/FundSERV requirements
Investor issuance: Bonus shares must be issued to every investor within the CUSIP. Isolating specific investors inside a CUSIP will stop firms from supporting the issuance.
Hard-lock restrictions: A sponsor cannot apply hard-lock restrictions to shares and expect them to hold through FundSERV. Many transfer agents have built controls and processes to restrict bonus shares by age, yet most custodians and National Securities Clearing Corporation (NSCC) FundSERV tool providers do not track the data point, and FundSERV carries no layout for restriction data.
Redemption fee restrictions: When redemption fees are based on share age, structure them inside FundSERV’s existing short-term trader or contingent deferred sales charge (CDSC) framework, so the firm and transfer agent can track the fee across the platform and process it through the standard FundSERV data flow.
Periodic products give a sponsor more room. Because the transfer agent holds the shares and owns the tools to enforce specific terms, agreements can be structured across distribution partners with far greater flexibility.
Periodic NAV/AIP requirements
Investor issuance: Certain investors can be isolated within a CUSIP because the transfer agent holds the shares and can enforce the requirement.
Hard-lock restrictions: Hard-lock restrictions apply when the shares are held and restricted at the transfer agent. Ultimus Fund Solutions has built dedicated controls and processes to restrict bonus shares by age. Most custodians and NSCC FundSERV tool providers still do not track the data point, so restricted bonus shares call for a transfer agent that has intentionally built hard-lock tooling.
Redemption fee restrictions: When redemption fees are based on share age, structure them inside FundSERV’s short-term trader or CDSC framework, so the firm and transfer agent can track the fee across the platform and process it through the standard data flow.
“You must have a transfer agent that has intentionally designed tools around hard lock functionality to offer bonus shares with a restriction.” |
The operating environment matters as much as the NAV cycle. A position held in an omnibus account behaves differently from a position carried at Matrix Level 3, and the two structures do not surface the same account-level detail. A program that assumes visibility into underlying investors can break the moment the shares sit inside an omnibus position, so map the account structure before committing to a restriction or an aging rule.
How the shares get issued
Putting bonus shares on the books is where programs diverge, and several issuance methods have surfaced. None solves for every constraint, and each carries a different operational and tax footprint. Two decisions drive most of the tradeoffs: how the shares are booked, and when they are issued, either upfront at purchase or at the end of a holding period. Issuing upfront is close to impractical for a daily NAV product today. A periodic structure can sometimes get there.
The methods, in brief:
Stock award/issuance: Shares are granted at a zero-cost basis. The method aligns closely with existing processing and creates minimal system disruption. The investor recognizes the full gain at redemption.
Share adjustment: Share count increases, and the existing basis spreads across the enlarged position. The structure is conceptually familiar but calls for manual lot adjustments.
Stock split: Basis is diluted across the cost lots through a split mechanic. The structure is familiar, though intermediary support is limited.
Return of Capital (ROC): Special distribution is reclassified as return of capital using existing distribution rails. The approach requires a year-end reclassification and reports through the 1099-DIV.
As-of/Fully loaded purchase: Original purchase is adjusted to reflect the bonus. The method aligns with standard gain and loss treatment but forces retroactive adjustments and can break AIP.
Cancel and rebook: Original trades are rebooked at an adjusted share count and price. Economic value stays consistent, but the approach is disruptive to systems and tax lots.
A clawback or penalty overlay can sit on top of any of the methods above when the program ties bonus shares to a holding period.
Our read: under today’s infrastructure, the stock award method is the most practical starting point. The method fits existing processing and limits system change, though it still calls for partner coordination and a clear tax conversation with investors.
Cost basis and tax reporting
The cost basis and tax treatment of bonus shares have evolved. When the shares are issued as a dividend stock issuance, the transfer agent must run a specific process to redesignate the stock dividend appropriately within the 1099-DIV. When the shares are issued as a straight stock purchase or issuance, the sponsor must tell the transfer agent how to treat the shares for cost basis and 1099-B reporting. Two basis approaches are common: zeroing out the basis on the bonus shares, or diluting the existing basis across the lots the bonus applies to.
Clawbacks add another dimension. A clawback rarely reduces to a single percentage. The program has to isolate the specific fee codes and descriptions, and often needs an escrow bucket or a letter-of-intent lockdown that the industry data tools may not carry cleanly. When a clawback crosses a tax year, the reporting consequences multiply, and a sponsor should decide upfront whether dividend distributions count toward the clawback calculation. Work through the treatment with your tax and legal advisors early. An unexpected tax liability at redemption creates a poor experience for investors involved.
Bonus share tracking and reporting
The transfer agency running the program has to genuinely understand bonus shares. The service provider needs the right technology to produce accurate reporting for bonus share aging, fee tracking, hard-lock aging, and fee collection across the repurchase and tender cycle. Look for a holistic support structure. Many providers claim a full-service offering, then leave the sponsor to track all of the aging.
Summary of operational risks
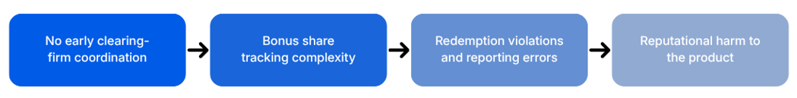
Clearing firm resistance: The primary hurdle in the current environment is clearing firm resistance. Because bonus shares can move through complex utilities such as FundSERV, the program must be designed around a clear understanding of each clearing firm’s expectations.
Coordination requirements: A sponsor should engage clearing firms early, keep open communication channels, and confirm every firm understands how the bonus share program will be offered and supported.
Operational impact: Without early coordination, the complexity of tracking bonus shares can lead to redemption violations, reporting errors, and, in the worst case, reputational harm to the product.
In conclusion
Bonus shares are not a shortcut to the distribution of retail alternatives. Bonus shares are a long-term tool that needs to be used wisely, in partnership with your transfer agent, your distribution partners, and, most importantly, the large clearing firms they use for trading. Ultimus has helped lead the development and implementation of bonus share programs from the outset. Few firms in the industry are as willing, or as prepared, to partner with sponsors and guide them through the process.
COD00001097